

Nearly one-third of Bangladesh’s total bank loans have turned non-performing, with an estimated 80 to 90 percent of the defaulted loans unlikely to be recovered, exposing the banking sector to a deepening crisis of bad debts and capital shortages.
The sector’s NPL ratio stood at 32.78 percent in June 2026, while its capital adequacy position slipped to a negative 2.64 percent at the end of 2025, leaving banks with little capacity to absorb mounting loan losses, according to a new research report.
Banks also faced a provisioning shortfall of Tk191,441 crore, while Tk182,419 crore remained stuck in 845 cases due to court-imposed stay orders, further obstructing recovery efforts.
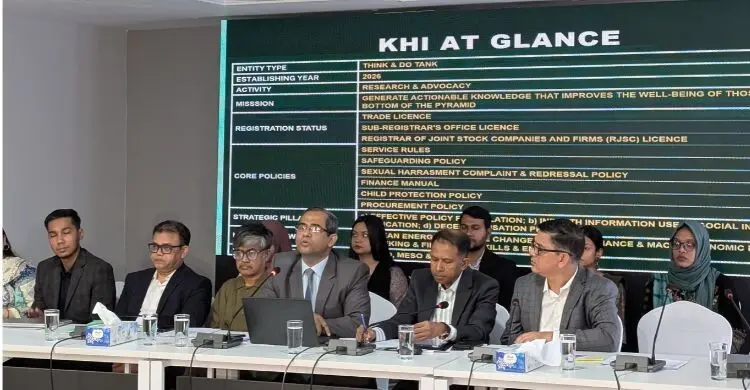
The findings were presented in a report titled Banking Sector Assessment and Policy Review: January-September 2026, prepared by the Knowledge Hub Institute.
Research Associate Noor Yana Jannat presented the report at an event in Shyamoli, Dhaka, on Saturday, attended by Knowledge Hub President Khandaker Golam Moazzem and members of its board of trustees.
Shah Md Ahsan Habib, component lead at the institute, described the scale of defaulted loans as alarming, warning that banks lacked sufficient capital to absorb the losses.
He said a large portion of the classified loans had already fallen into doubtful and bad categories, making recovery highly uncertain.
Habib estimated that less than 10 percent of the reported NPL burden represented conventional credit risk, while the rest was linked to operational failures, irregularities and alleged criminal activities.
Addressing such problems required coordinated action by banks, the government and the central bank, rather than relying on lenders alone, he said.
He also warned that deliberate loan defaults were shifting the burden onto ordinary depositors, bank employees, responsible businesses and financially sound banks.
Good borrowers were having to pay higher interest rates, while the weaknesses of troubled banks were affecting the wider economy, he added.
Islamic banks in the worst position
The report revealed sharp differences in loan quality across banking groups.
State-owned banks recorded an NPL ratio of 43.2 percent, while the rate stood at 31.6 percent for private commercial banks and 6.5 percent for foreign banks.
Full-fledged Islamic banks were in the weakest position, with 58.9 percent of their loans classified as non-performing.
Their deposits declined by 1.7 percent, while the loan-to-deposit ratio climbed to 127.7 percent, indicating mounting pressure on their funding position.
Credit growth slows despite rising deposits
Despite strong deposit growth, banks’ lending to the private sector continued to lose momentum, the report said.
Bank deposits grew by 11.96 percent in August, but private-sector credit growth was only 4.75 percent. It slowed further to 4.09 percent in September.
Banks held excess liquid assets worth Tk441,954 crore in August. However, the report cautioned that surplus liquidity across the banking system could conceal liquidity problems at weaker banks.
The report also identified significant gaps in financial inclusion.
SME loans accounted for 15.87 percent of total bank lending in March, against a target of 25.50 percent. The share of loans to women entrepreneurs was 7.28 percent, compared with the target of 15 percent.
Rural areas accounted for 16.25 percent of total bank deposits but received only 7.42 percent of bank credit. Meanwhile, 34.48 percent of agricultural and rural loans were overdue in August.
Urgent bank reforms recommended
To contain the crisis, Knowledge Hub recommended independent reviews of loans at vulnerable banks by December 2026 and decisions on bank-specific capital restoration or resolution by March 2027.
It also called for regular disclosure of loan recovery, capital positions and customer service performance to improve transparency and accountability.
The report took note of the Bank Resolution Act 2026, the Deposit Protection Act 2026 and the proposed Tk35,000 crore capital framework for the consolidated Islamic bank.
However, it said there was no evidence that the process of returning depositors’ money at the consolidated Islamic bank had been completed.
On the broader economic front, inflation stood at 8.34 percent in September, while the policy interest rate remained unchanged at 9.50 percent.
Foreign exchange reserves reached $31.20 billion on September 30, while remittance inflows grew by 13.28 percent during July-September.